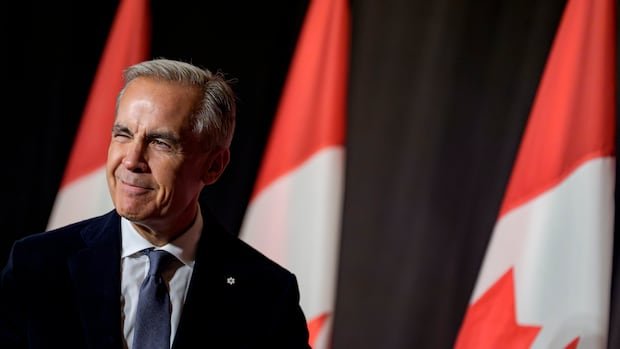

The Canadian government unveiled a significant tax reform during the Canada Investment Summit, introducing a productivity mega-deduction that enables businesses to write off investments. This deduction covers the total cost of new investments in various sectors such as machinery, equipment, clean energy, and zero-emission vehicles.
Prime Minister Mark Carney stated the government’s aim is to position Canada as the most appealing G7 country for investment. This initiative expands on the previous productivity super-deduction outlined in the last year’s budget, which initially covered only a limited range of investments. With this expansion, approximately two-thirds of assets will now be eligible for deduction.
Carney emphasized that broadening the sectors eligible for the deduction will empower business leaders to invest strategically, ultimately enhancing productivity in Canada. This move is expected to make the country more competitive in terms of taxation compared to its G7 counterparts, reducing the marginal effective tax rate to 6.4 percent.
The tax reform, while estimated to cost $36 billion over five years, is seen as a strategic step to incentivize companies to invest and boost economic growth amid challenges like trade wars. Economists like Randall Bartlett and Jim Stanford have expressed support for the program, highlighting its focus on driving reinvestment in Canada.